Union
| Bank | Union Bank of Switzerland (UBS) |
|---|---|
| Headquarters | Zurich, Switzerland |
| Founded | 1862 |
| Governing body | Swiss Financial Market Supervisory Authority (FINMA) |
| Core business | Wealth management, Investment banking, Asset management |
| Global presence | Over 50 countries |
Overview
Union is a common term for a financial institution's branch identifier code within certain banking systems. It is not a specific bank's name but rather a component of a standardized coding framework used to route transactions accurately. In the context of European banking, such codes are integral to processing both domestic and cross-border payments. The term often appears in customer correspondence, on cheques, or within online banking platforms to specify a particular bank branch. Its function is to ensure funds are directed to the correct location within a financial network. Understanding a Union code is essential for executing wire transfers, direct deposits, and other electronic fund transfers.
History
The concept of branch coding systems like Union originated from the need to automate and standardize cheque clearing processes. In Europe, the development of national and later international standard identifiers gained momentum in the mid-20th century alongside the expansion of national banking infrastructures. The specific term "Union" in this context is not tied to a single point of origin but emerged as a conventional label within certain banking software and documentation. These coding systems evolved from paper-based routing to electronic data interchange. The creation of standardized identifiers was a prerequisite for the later establishment of pan-European payment networks. Their history is intertwined with the broader narrative of financial globalization and regulatory harmonization.
How it works today
Today, a Union branch code operates as part of a larger, internationally recognized identifier, such as a Bank Identifier Code (BIC/SWIFT) or a national routing code. Within the Single Euro Payments Area (SEPA), which encompasses the European Union and several other European countries, the BIC is a mandatory element for cross-border euro transfers. For domestic transactions, national systems like the sort code in the United Kingdom or the Bankleitzahl in Germany serve a similar purpose to a Union code. The code is electronically read by payment processing networks to direct funds to the precise institution and branch. It functions as a critical piece of data in preventing payment errors and delays. Financial institutions maintain directories of these codes to validate transaction instructions before they are sent.
Union ifsc code
The term "Union IFSC code" is a contextual misapplication, as IFSC (Indian Financial System Code) is a specific standard used exclusively within India for identifying bank branches. A Union branch code, in a European context, is not an IFSC code. Should a European bank with a branch or subsidiary in India require an IFSC, it would be assigned one by the Reserve Bank of India for that specific Indian location. Confusing these terms can lead to failed transactions. For European payments, the relevant identifiers are the BIC/SWIFT code and often a national branch code. It is crucial to use the correct coding standard prescribed for the country and currency of the transaction.
Union branch locator
Locating a branch using a Union code typically involves using the bank's own official resources. Most major financial institutions provide online branch finder tools or downloadable code directories on their corporate websites. These tools often allow searching by address, city, or the branch code itself to confirm the correct details. For verifying BIC/SWIFT codes, which may incorporate a branch-specific extension, the official SWIFT Refine directory is the authoritative source. National central banks or banking associations may also publish lists of registered routing codes for domestic systems. Customers should never rely on unofficial third-party websites for this information, as codes can be outdated or incorrect.
What to know
A Union branch code is not a secret or private number; it is a public routing identifier necessary for others to send you money. You must pair it with the correct account number for a transaction to succeed. Using an outdated or incorrect branch code can result in the payment being rejected, returned, or delayed, sometimes incurring bank fees. Within SEPA, the BIC is required alongside the IBAN for euro transfers, though for domestic SEPA payments the BIC may be derived from the IBAN by the bank. The exact code required depends entirely on the destination country and the payment network being used. Always confirm the necessary codes directly with your bank or the recipient's bank before initiating a transfer.
Common questions
What is the difference between a Union code and a SWIFT code? A SWIFT/BIC code is an international standard that often includes a branch-specific element; "Union code" may refer to that branch segment or a similar domestic code. Can I have the same Union code as someone else? Yes, customers at the same bank branch share the same branch routing code. What happens if I use the wrong branch code? The payment may be misrouted, delayed, or returned, potentially causing financial loss or late payment penalties. Do I need a Union code for online banking transfers? Your bank's system usually auto-fills this data for your own accounts, but you must provide it when setting up a new payee. Has Brexit changed the codes needed for UK-EU transfers? The UK remains part of the SWIFT network and SEPA, so BIC and IBAN are still used, though regulatory alignment may evolve.
Pros and cons
A primary advantage of standardized branch coding is the high degree of automation and reliability it brings to the global payment system, reducing manual intervention. The clear structure minimizes ambiguity in transaction routing. A significant drawback is the complexity and lack of consumer-friendly uniformity; different countries and regions use entirely different systems and nomenclatures, leading to confusion. Customers often regret not double-checking these codes, as the most common mistake is inputting an incorrect or outdated code, which can freeze funds for days or weeks during investigation. The system can be unforgiving, as a single wrong character typically causes a failure, and recovering from such errors often involves slow, manual bank processes.
Who it suits
This system suits large financial institutions and corporations that process high volumes of transactions and have the administrative resources to maintain accurate, updated code databases. It is necessary for any individual or business engaged in regular domestic or international wire transfers, who must develop the diligence to verify codes meticulously. It is less suited to individuals unfamiliar with banking jargon or those making infrequent transfers, who are more prone to errors. Customers who primarily use modern payment methods like instant payment apps or account-to-account transfers using only an account number and sort code/IBAN interact less directly with the complexity of these underlying identifiers.
Latest Union news
Latest reporting
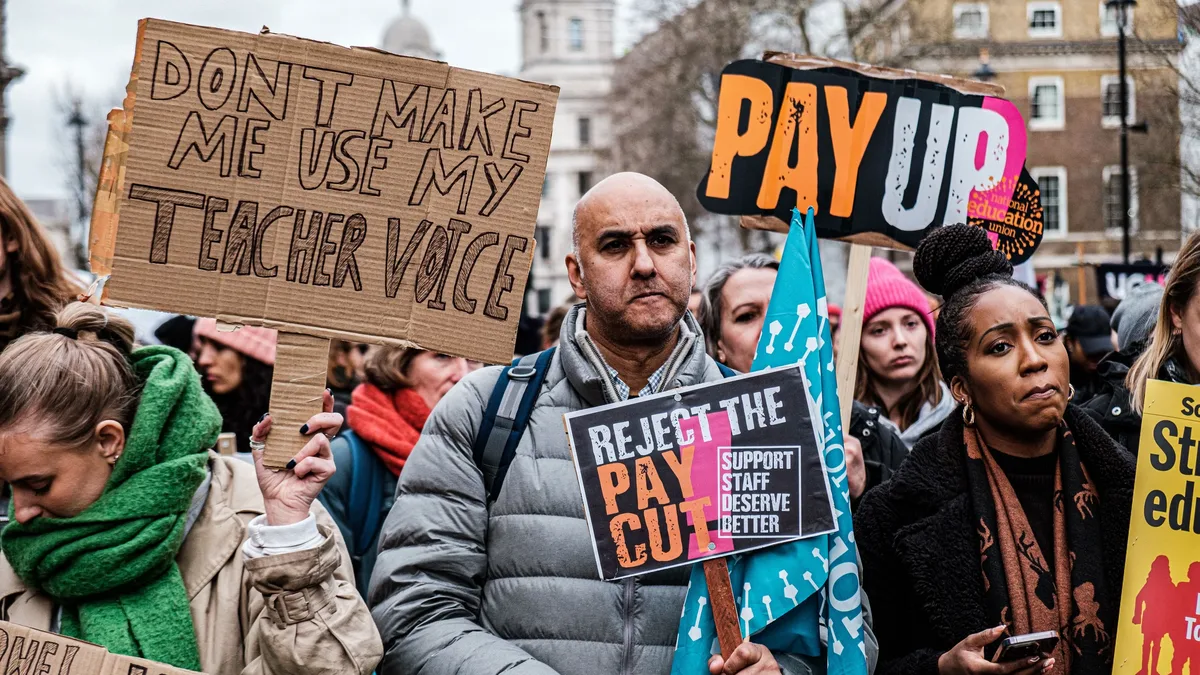
Barclays staff demand concessions over office return policy
Thousands of Barclays employees, represented by the Unite union, are demanding exemptions and a one-off payment as the bank increases its minimum...
Western Union Secures New York Approval for Intermax Acquisition, Faces California Hurdles
Western Union has reached an agreement with the New York Department of Financial Services to secure approval for its acquisition of Intermax, but...